Table of Contents
Points Miles and Bling (blog) contains referral or affiliate links. The blog receives a small commission at no additional cost to you. Thank you for your continued support. Credit Card issuers are not responsible for maintaining or monitoring the accuracy of information on this website. For full details, current product information, and Terms and Conditions, click the link included.
Capital One just launched new credit cards in Canada and wow! These cards certainly make an impact. Capital One just launched the Quicksilver World and Quicksilver World Elite in Canada, featuring no annual fees, no foreign exchange fees, and an effective 6% back on groceries, gas, and EV charging in the first year.
At a Glance:
Both cards have no annual fee, the same earn rate and no foreign transaction fees. Each earns 3% on groceries, gas, and EV charging and 1% on everything else.
Earn a welcome bonus of an unlimited dollar-for-dollar match of all cash back earned in the first year.
Welcome Bonus
On both cards, Capital One is offering double cash back in the first year with no limit. That’s effectively 6% back on eligible grocery, gas, and EV-charging purchases and 2% everywhere else on cash back that posts during the first 365 days after account approval.
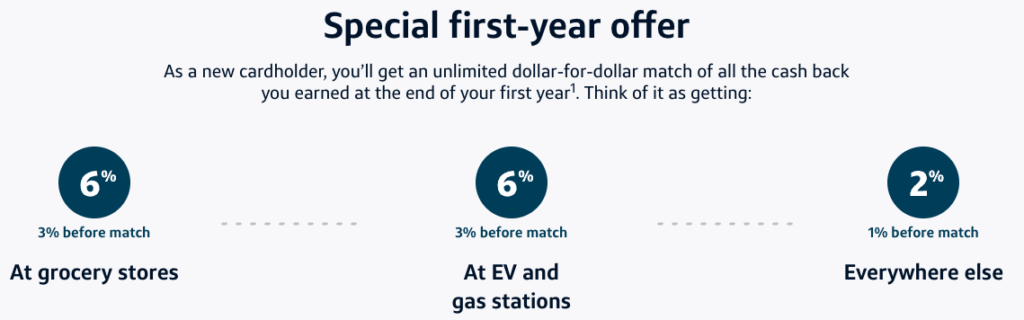
Capital One Quicksilver welcome bonus
The “no limit” part is particularly fascinating. If you spend $2,000 a month between groceries, gas, and EV charging, that’s $24,000 a year and $720 of cash back at 3%. With the first-year match, that becomes $1,440, assuming every purchase qualifies for the 3% category and posts during the match period.
The cash back match is calculated at the end of the first 365 days and credited within two billing periods.
Make sure you see the cash back match offer on the Capital One website when applying, as Capital One specifically writes “This offer is only available when displayed on this site.”
Earn Rate & Features
The Capital One Quicksilver World Elite and Capital One Quicksilver World earn 3% cash back at grocery stores, gas stations, and EV charging with no spending cap and no maximum on cash back earned. In the first year, double that to 6% cash back.
For groceries, this applies at Merchant Category Codes (MCC) 5411, 5422, 5451, and 5499. Superstores like Walmart and Costco are excluded.
For gas and EV charging, MCCs 5542, 5541, and 5552 are eligible.
On the “everything else” category, earn an unlimited 1% back, or 2% in the first year when taking into account the welcome bonus.
Quicksilver World Elite vs. World
When considering which to apply for, the main difference for anyone who pays their balance in full comes down to the income requirements. Both have the same rewards structure and insurance package.
Income Requirements
The World Elite has a higher income requirement of $80,000 personal or $150,000 household. The World has an income requirement of $50,000 personal or $80,000 household.
Insurance Coverage
As a card with no annual fee, the insurance package is actually pretty decent:
- Purchase protection
- Extended warranty
- Car rental collision/Loss Damage Insurance on rentals up to 31 days
- Price Protection
- Common Carrier Travel Accident Insurance
- Flight Delay Insurance
- Baggage Delay Insurance
- Lost Baggage Insurance
Full details on the Certificate of Insurance.
Are the Capital One Quicksilver Cards Worth It?
For cash back fans, these are among the strongest first-year offers in Canada, particularly for anyone with substantial grocery, gas, or EV-charging spending. The uncapped match is what makes the offer unusual: high spenders are not boxed in by a promotional spending limit.
Earning 6% cash back on groceries, gas, and EV charging with no limits for 365 days is reason enough to sign up, and I’m personally recommending this card to friends and family who want to earn rewards as cash. It’s an especially easy sell when the cards have an ongoing $0 annual fee, rather than simply waiving the fee for the first year.
No foreign transaction fees are just the icing on the cake, making it a great card for occasional travellers to use abroad. 0% FX fees on a card with no annual fee and solid earn rates is fantastic.
“Occasional” is the key word here because I believe that for many of the PMB audience, the upside of redeeming travel points for business and first class flights still outweighs any 6% cash back. For us, we’ll keep earning RBC Avion.
Takeaway
With no annual fee, no foreign transaction fees, and an uncapped first-year cash back match, the Quicksilver cards are an easy recommendation for anyone who prefers straightforward cash back. Earning an effective 6% on groceries, gas, and EV charging for an entire year is especially hard to beat.
For miles & points enthusiasts, I wouldn’t necessarily move spending away from transferable currencies like RBC Avion just to earn cash back. But for friends and family who don’t want to think about transfer partners, award availability, or maximizing redemptions, this is probably the cash back card I’d recommend first.
