
Table of Contents
Points Miles and Bling (blog) contains referral or affiliate links. The blog receives a small commission at no additional cost to you. Thank you for your continued support. Credit Card issuers are not responsible for maintaining or monitoring the accuracy of information on this website. For full details, current product information, and Terms and Conditions, click the link included.
Rogers x Chexy: Earn an Additional 1% Cashback Bonus Until May 10, 2027
Chexy’s latest partnership is here, and it’s an exciting one: use your Rogers card on Chexy to earn an additional 1% in cashback from now until May 10, 2027.
The following cards are eligible:
- Rogers Red World Mastercard
- Rogers Red World Elite Mastercard
- Rogers Red World Elite Business Mastercard
- Rogers Red World Legend Mastercard
All the above cards earn 2% cashback on all non-USD purchases if you have at least 1 qualifying service with Rogers, Fido, Shaw, or Comwave. Without a qualifying service, the Rogers Red World Mastercard earns 1% cashback on eligible non-USD purchases, while the Rogers Red World Elite and World Legend Mastercards earn 1.5%.
With this Chexy promotion, Rogers customers will earn 3% cashback on all spending through Chexy. There are a few important details to keep in mind, though:
- Bonus cashback may take up to 5 months to be paid out
- World Mastercard, World Elite Mastercard, and World Elite Business Mastercard accounts have a $10,000 rewards limit per account
- World Legend Mastercard accounts have a $25,000 rewards limit
I take the “rewards limit” to mean the spending cap; so you’ll earn 3% cashback on the first $10,000 spent on your Rogers Red World Elite Mastercard (for example), or a maximum of $100 in additional cashback.
Is Using Your Rogers Card on Chexy Worth It?
At first glance, no. The math isn’t mathing: why would you pay a 1.75% fee to earn an additional 1% back? But the answer is actually simple: the point of Chexy is to earn credit card rewards on spending you can’t typically put on a credit card.
Earning 3% back with a 1.75% fee (lower with referrals) works out to roughly 1.3% net cashback (the processing fee earns cashback, too) on items like rent, CRA tax payments, and more. Then, consider that all the Rogers cards except the World Legend have no annual fee, and this 1.3% really is free money.
The idea of using cashback cards on Chexy isn’t new: Scotiabank actually purposefully ended 4% cashback on rent and tax payments earlier this year. As such, it’s nice to see another cashback card take its place as a high-earning avenue on Chexy.
For those of us who prefer to earn travel points, we’ll keep using our travel rewards cards. But if you prefer to earn rewards in cold, hard cash, this Rogers and Chexy promotion is fantastic news.
| On a $2,000 payment | Amount |
|---|---|
| Chexy processing fee at 1.75% | $35 |
| Total charged to your card | $2,035 |
| Cashback at 3% | $61.05 |
| Net cashback after the fee | $26.05 |
For expenses like rent, property tax, and CRA tax payments, using Chexy is objectively better than not, because you earn 1.3% back compared to paying a bill from your bank account. Just keep in mind the earning cap because $10,000 can go quickly for major expenses.
But Chexy isn’t necessarily the default for your Rogers card: if you can pay the bill directly with no transaction fee, that’s still the better way to go because Chexy’s 1.75% fee does not offset an extra 1% in earnings.
What is Chexy, and why use it?
Put simply, Chexy is a Canadian payment platform that lets you earn credit card rewards on everyday expenses like rent, taxes, insurance, utilities, gym memberships, and other bills – turning expenses that traditionally cannot be paid for using credit cards into points-earning opportunities.
For many people, mortgage, rent and other fixed monthly bills are their largest expenses, but earning points on these expenses is not so straightforward. If your landlord only accepts cheques and e-transfers, it can feel a bit wasteful to miss out on points for a $2,000+ purchase every month, and with Chexy, you won’t have to.
Chexy payments can be recurring or one-time, so you can set them up based on the expense. You can set up rent as a recurring expense, while paying your child’s tutor can be a one-time transaction.
How Chexy Works
Sign up for a Chexy account, add your credit card(s), and then set up the payments you want to make through the platform. For example, this could be rent, taxes, tuition, the contractor building your patio, your child’s tutor or any other one-off or recurring expenses.
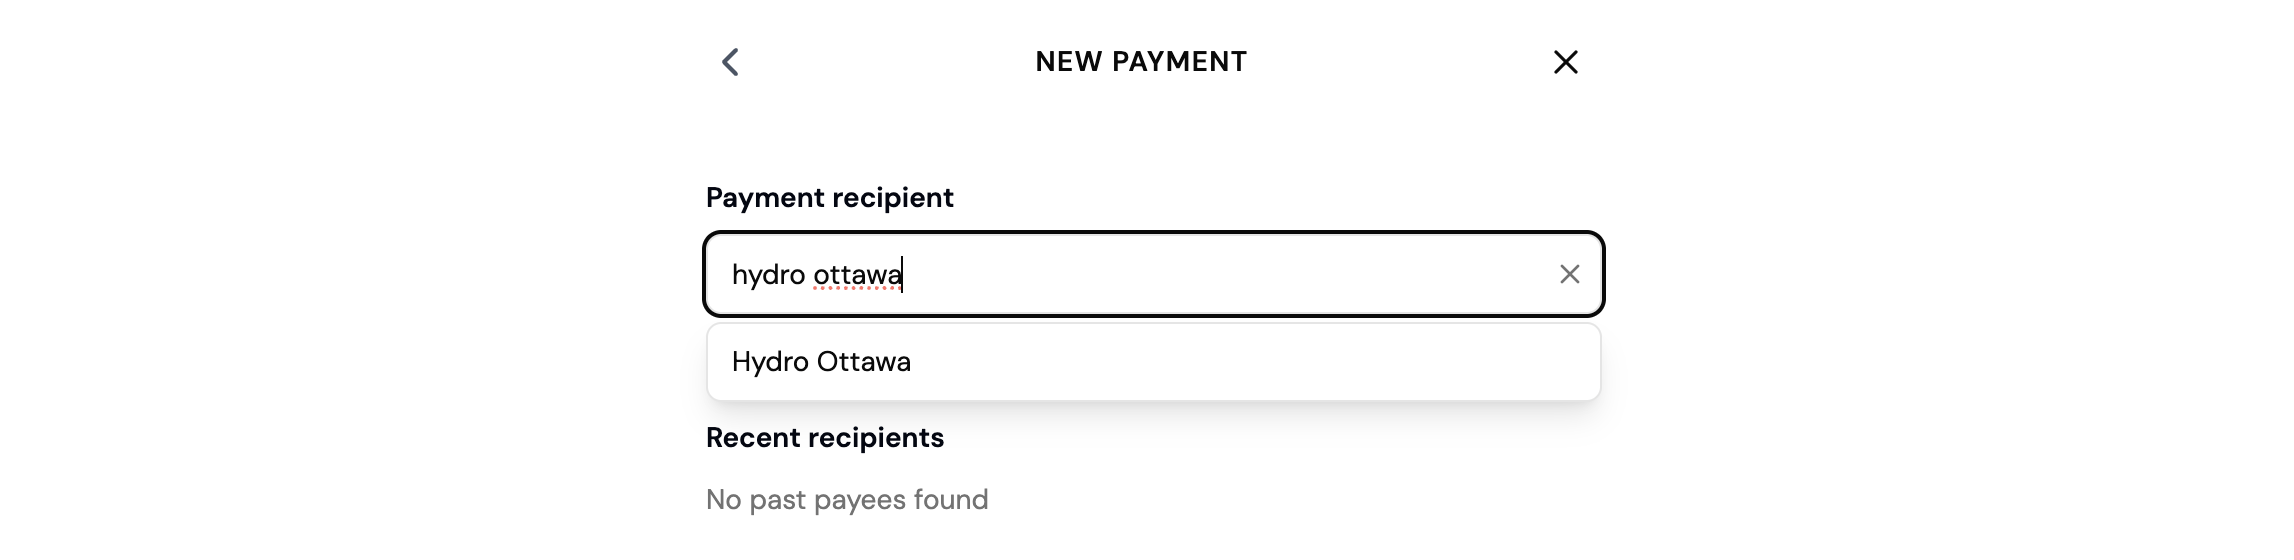
Think of Chexy as the middle layer between you and the payee. Chexy charges your credit card four days before the payment is due, then sends the payment on your behalf using the payee’s preferred payment method (compatible only with Interac e-Transfer, pre-authorized debit, or bill pay).
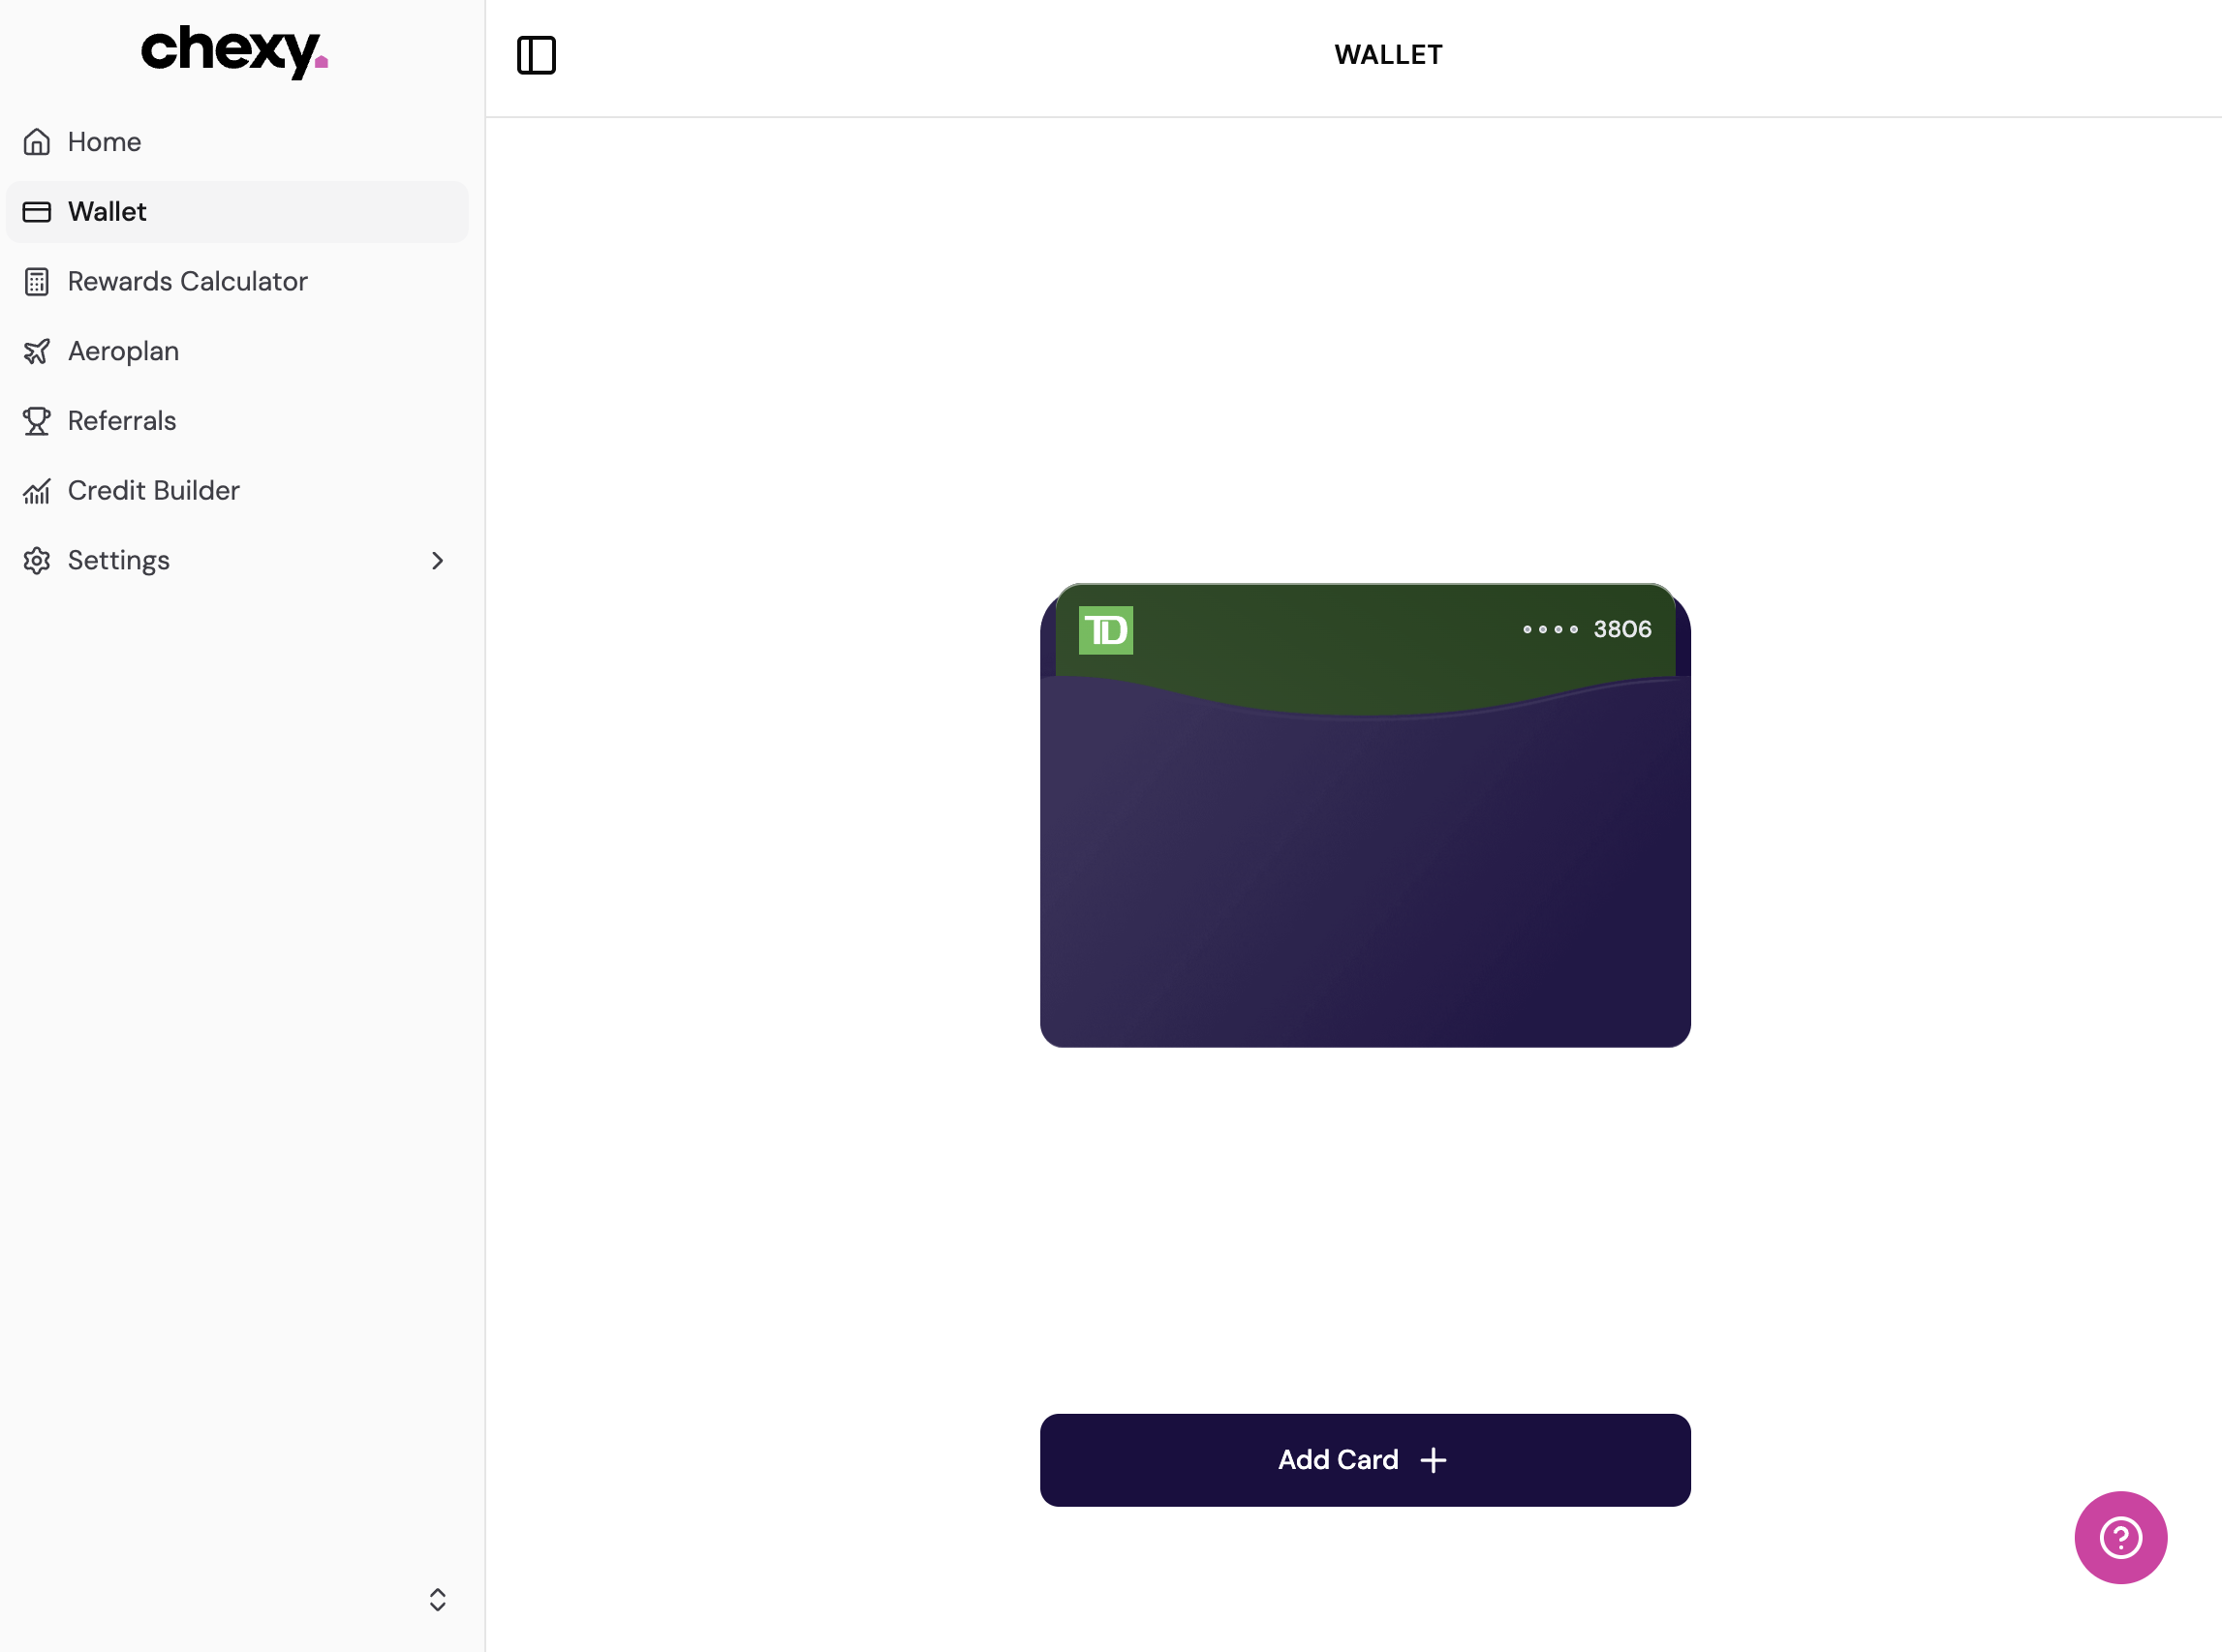
Recently, Chexy introduced the ability to add up to five credit cards to a single account, allowing you to choose the best card for each payment and therefore maximize rewards across different cards.
Does Chexy Charge Fees?
The short answer is yes – for Canadian Visa, Mastercard, and Amex cards, Chexy charges a 1.75% fee, while international credit cards are subject to a 2.5% fee.
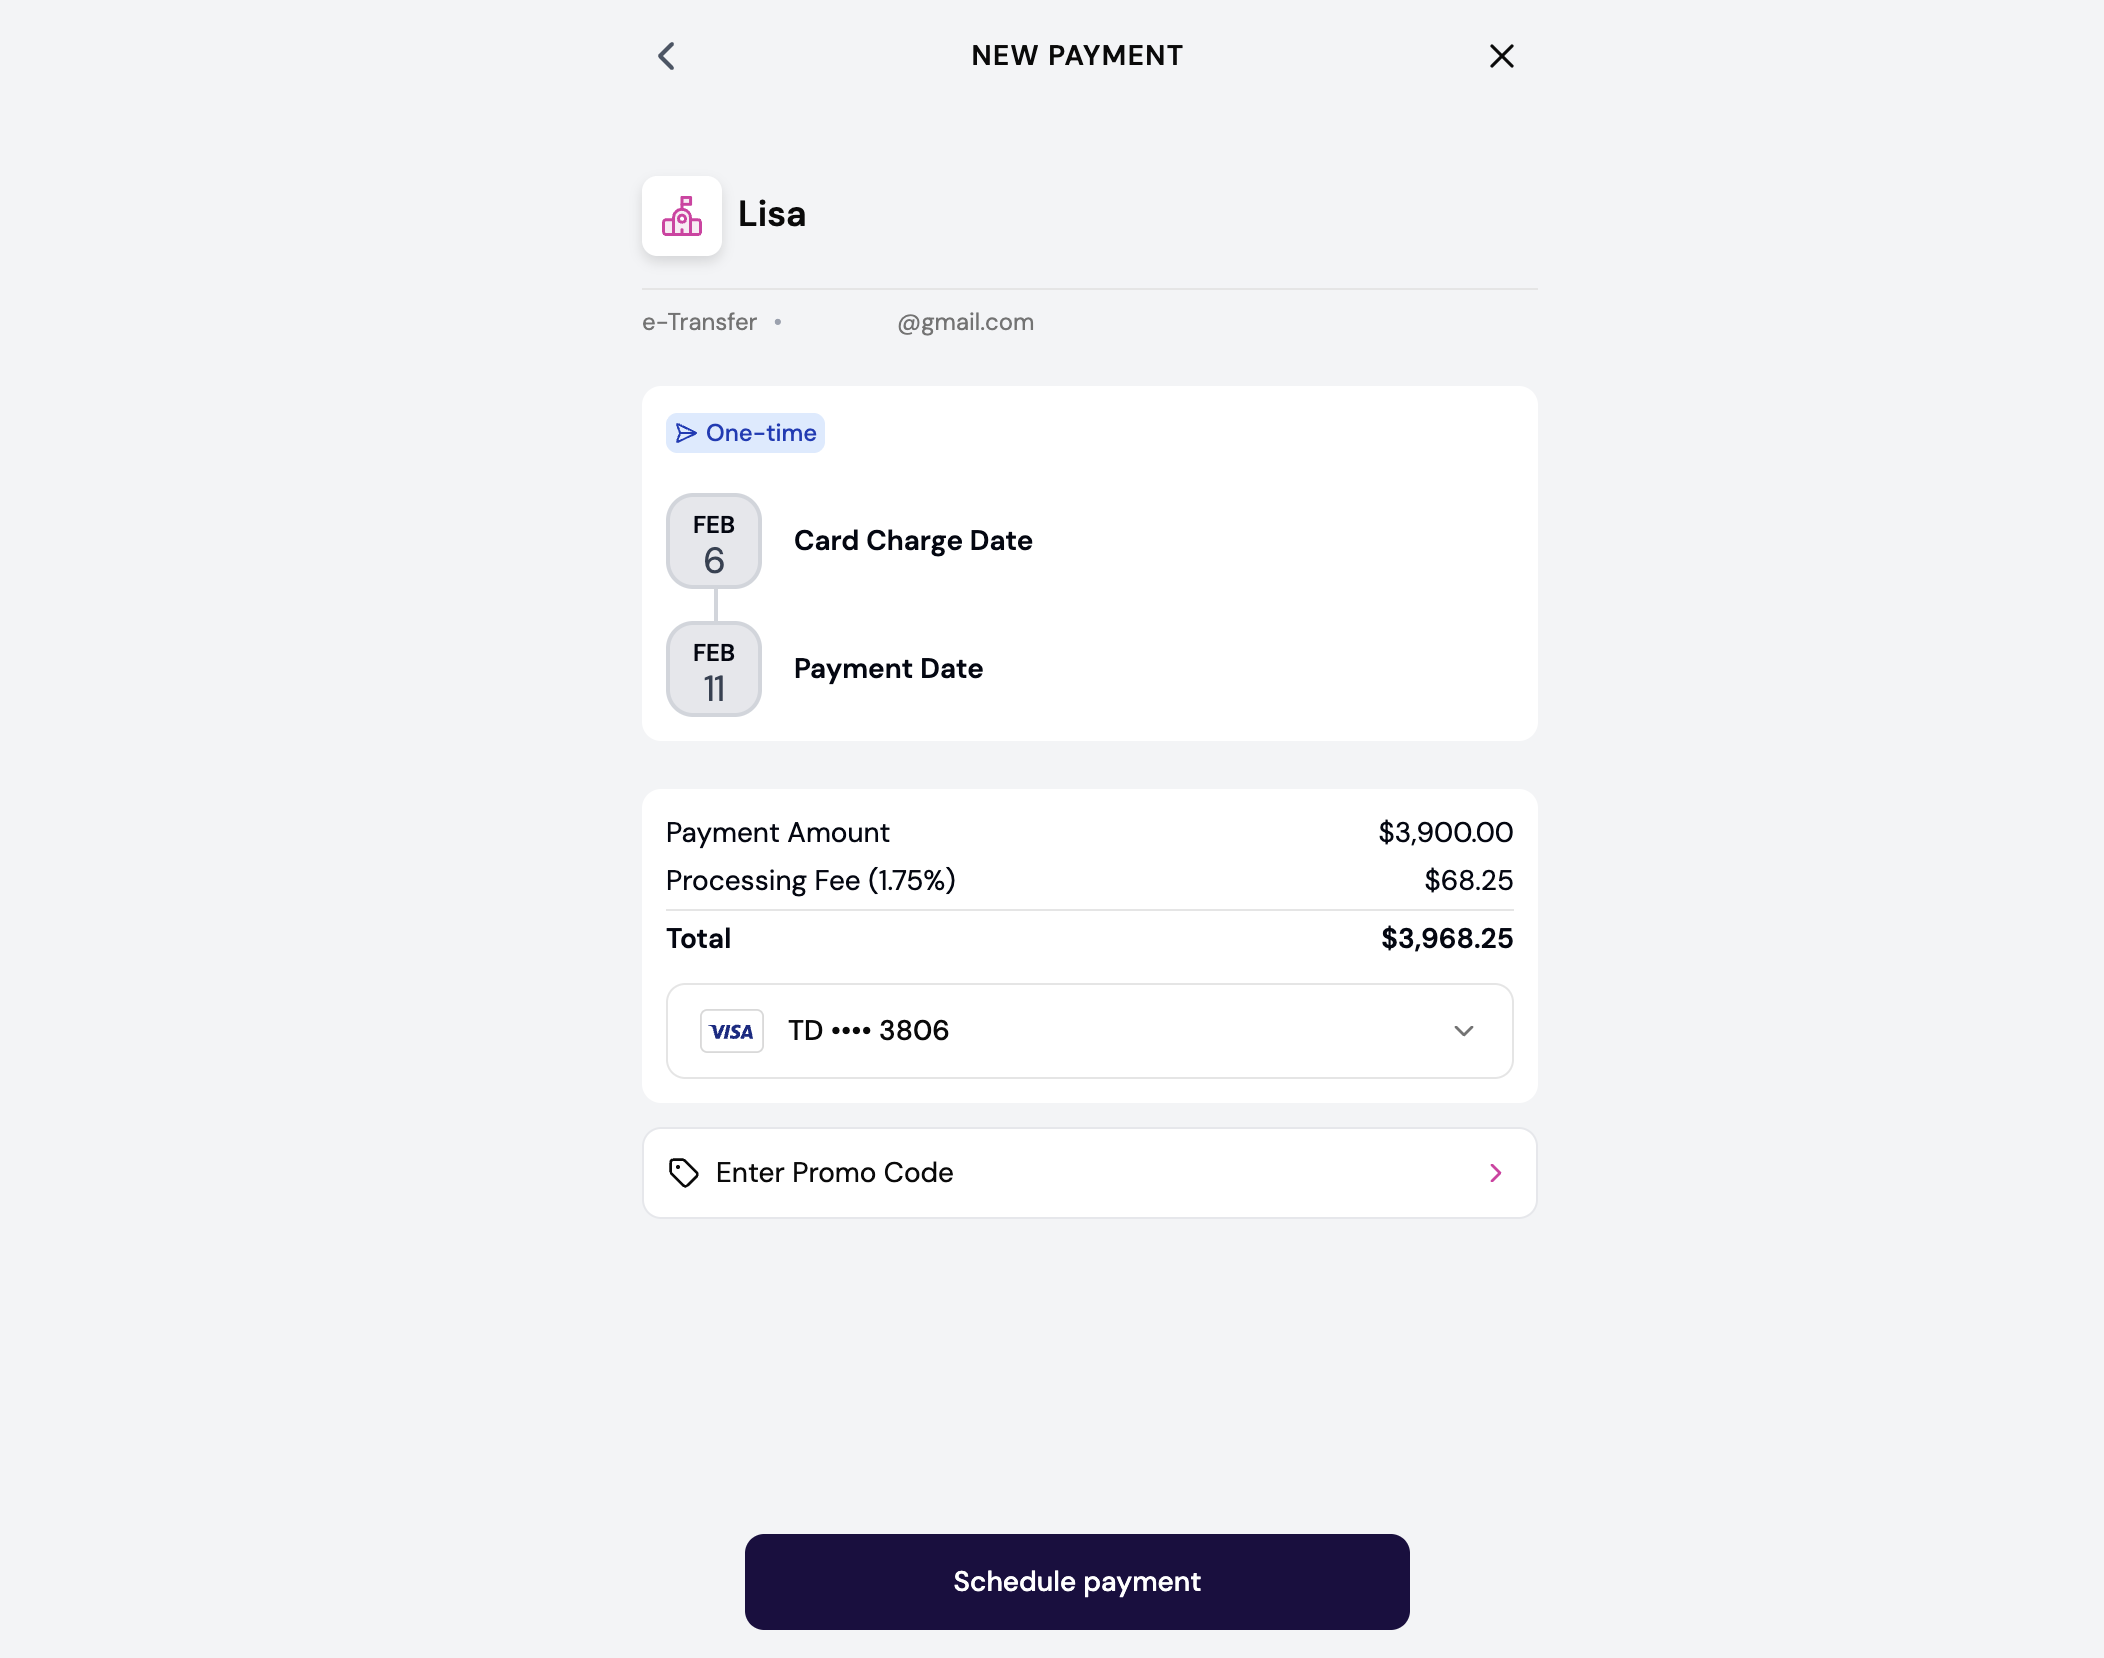 We know that all points are earned via the interchange fee Visa or Amex charges and traditionally paid by the vendor. In Chexy’s case, we can assume this fee is passed onto the customer, and per Chexy, the value of the points earned through these transactions is designed to fully offset the cost of the fees.
However, note that there are also opportunities to lower these fees through their referral program.
By referring friends to Chexy, you unlock lower processing fees on your own payments over time. If the friends you refer continue using Chexy, you can extend your referral status into the following year (new for 2026).
Can You Lower Chexy’s Fees?
Some existing users qualify for reduced fees through referral status. Chexy also offers optional paid memberships with lower processing rates on annual plans.
For Canadian credit card payments, annual Essential membership reduces the rate to 1.65%, while annual Plus membership reduces it to 1.5%. The annual memberships cost $90 and $200, respectively. Monthly memberships retain the standard credit card processing rate.
The subscription cost matters. Looking only at the domestic processing-fee savings, you would need approximately:
- $90,000 in annual payments to recover a $90 membership through a 0.10-percentage-point saving.
- $80,000 in annual payments to recover a $200 membership through a 0.25-percentage-point saving.
Other membership features may have value, but a lower advertised processing rate doesn’t automatically make a subscription worthwhile.
Lowering Chexy Fees via Referral Program
Chexy currently advertises $25 for you and the person you refer under its referral program. There is currently a holiday promotion offering milestone bonuses for referrals made between November 1 and December 31, 2026.
| Qualifying referrals | Additional milestone bonus |
|---|---|
| 2 | $100 |
| 4 | A further $300 |
| 6 | A further $600 |
To count as a qualifying referral, the person you refer must complete their first payment and a cumulative total of $1,000 in payments (before fees) within 90 days of creating their account.
Chexy also offers processing-fee discounts based on how many friends you refer. This is now a legacy feature because you can’t unlock referral statuses if you haven’t referred anyone by October 31, 2026, and the entire Status Tiers program with discounted processing is being phased out entirely in 2027. For now, you get:
|
Status |
# of referrals |
What you get |
What your friend gets |
|
Starter |
1+ |
$25 cashback |
$25 cashback |
|
Pink |
3+ |
$25 cashback + 1.5% fee |
$25 cashback |
|
Gold |
5+ |
$25 cashback + 1.0% fee |
$25 cashback |
|
Elite |
10+ |
$25 cashback + 0.5% fee |
$25 cashback |
Note: decreased processing fees apply only when using Canadian credit cards (more on international cards later).
Last Time to Extend Lower Processing Fees Through Referrals
Since Status Tiers are being phased out, this is the last opportunity to extend your status and its associated lower processing fees into 2027.
|
Your status |
Completed payments by December 31, 2026, by the people you refer |
|
Pink |
15 |
|
Gold |
50 |
|
Elite |
250 |
To be clear, only your existing status extends to 2027, so if you refer 5 people (Gold) and those 5 people complete 250 payments, your Gold status would extend, and you do not “upgrade” to Elite status.
For users paying with international credit cards, the referral program works slightly differently. Instead of moving to a fixed reduced fee, each referral status provides a discount off the higher international rate.
- 3 referrals: processing fee is discounted 0.25% = now 2.25% (Pink)
- 5 referrals: processing fee is discounted 0.75% = now 1.75% (Gold)
- 10 referrals: processing fee is discounted 1.25% = now 1.25% (Elite)
Regardless of the credit card used (Canadian or international), discounts apply only to the first $50,000 spent. Any dollars you spend through Chexy beyond that will be charged at the regular rate.
Chexy and TD Aeroplan Exclusive Partnership – Offer Ends October 14 2027
The way you get to as much as 2.25 Aeroplan points per dollar is simple: your TD Aeroplan card earns its usual rate of up to 1.25 points per $1, then Chexy adds another 1 Aeroplan point per $1 on eligible bill payments.
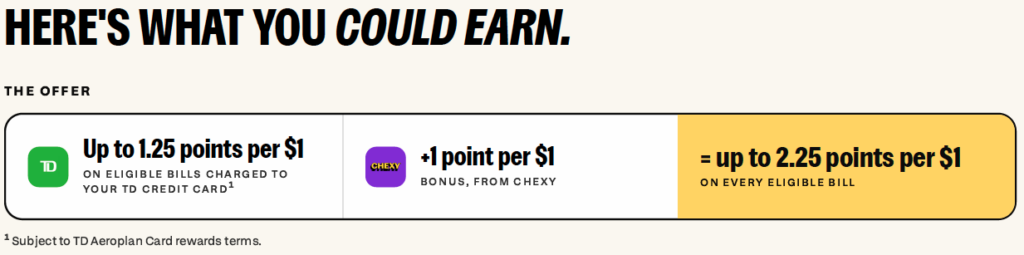
To be eligible for the extra 1 Aeroplan point per dollar, you must have applied and been approved for your TD Aeroplan card through the link provided by Chexy after logging in to your Chexy account. Existing cardholders are not eligible, and this offer ends October 14, 2027.
Then add your new TD Aeroplan card to Chexy and use it to pay existing bills. Points earned from your TD Aeroplan card show up on your TD monthly statement and online accounts, while the 1 Aeroplan point per dollar lands directly in your linked Aeroplan account.
Bonus points earned via Chexy only apply for the first 12 months and are capped at $25,000 in spend.
Up to 2.25 Points per Dollar Spent on TD Aeroplan Cards
Chexy advertises up to 2.25 points per dollar earned on the TD Aeroplan cards because each card offers a different earning rate congruent with its tier in the TD Aeroplan ecosystem. Chexy falls under the “all other purchases” category:
- TD Aeroplan Visa Platinum Credit Card: 0.67 points per $1 spent (1 point per $1.50 spent)
- TD Aeroplan Visa Infinite Card: 1 point per $1 spent
- TD Aeroplan Visa Infinite Privilege Card: 1.25 points per $1 spent
If you’re deciding which tier of Aeroplan card to apply for, consider if you want to spend your way to Aeroplan Elite status, want the 10% Head Start status benefit, or if you only care about a free checked bag.
The new 10% Head Start will take the place of rollover SQM
Only the TD Aeroplan Visa Infinite Privilege Card offers the former benefits, along with unlimited Maple Leaf Lounge access, priority check-in, and Zone 2 boarding. It also acts as the de facto Hyatt co-branded card because of Hyatt and Aeroplan reciprocal perks. The annual fee is going up from $599 to $699 in January 2027, so I recommend applying before then. Come January, you can take advantage of the new $50 x 2 Air Canada wallet credits and worldwide Maple Leaf Lounge access.
If you mainly care about the checked bag, the $139 TD Aeroplan Visa Infinite Card fits the bill, though the fee also rises to $159 in January. Again, apply before then to take advantage of the new $25 x 2 Air Canada wallet credits at the current annual fee.
Is Signing Up for A TD Aeroplan Card via Chexy Worth It?
For the most part, the math checks out. If you’re going to apply for a card anyway, you might as well apply through Chexy so you don’t miss out on the chance to earn an extra 1 Aeroplan point per dollar.
Do note that Chexy charges a 1.75% fee (lower if you have referrals), so you’re effectively buying Aeroplan points for 1.75 cents each (since you’d earn up to 1.25 points per dollar anyway on non-Chexy transactions). However, if you consider that you’re paying bills you couldn’t otherwise pay with a credit card, the math is admittedly pretty good.
With the TD Aeroplan Visa Infinite Privilege, you’d earn 2.25 Aeroplan points per dollar, which works out to about 0.78 cents per point.
The return is slightly weaker on the lower-tier cards: 2 points per dollar on the Visa Infinite works out to about 0.88 cents per point, while 1.67 points per dollar on the Platinum works out to roughly 1.05 cents per point.
Chexy can also make it easier to earn a new card’s welcome bonus by helping you meet the minimum spend through bills you already pay. Add the extra 1 Aeroplan point per dollar, and the value stacks up quickly.
If you’re already using Chexy with another credit card, switching those payments to a TD Aeroplan card could mean giving up rewards you currently earn elsewhere. Compare what you’d lose on your existing card, but with the extra 1 Aeroplan point per dollar, TD could still come out ahead.
Paying Mortgage with Chexy
Since August 2026, Chexy also offers earning Aeroplan points on mortgage payments.
No credit cards allowed, but you earn 1 Aeroplan point per $1 of mortgage payments and 1 SQC for every 5 Aeroplan points earned. The SQC counts towards the 25,000 SQC maximum in the “Everyday Partners” category.

At the standard 1.75% fee, a $2,500 monthly mortgage payment produces:
| Over one year | Amount |
|---|---|
| Mortgage payments | $30,000 |
| Chexy fees | $525 |
| Aeroplan points | 30,000 |
| SQC | 6,000 |
Referral-status discounts don’t reduce the mortgage fee. Chexy lists a 1.5% mortgage rate for annual Plus members, but don’t forget to include the membership cost in your calculation.
Is Chexy Worth it For Mortgage Payments?
For most things Chexy, I say yes because you earn rewards on a credit card. However, with mortgage payments, you don’t earn any additional credit card rewards, so the only benefit here is earning Aeroplan points and subsequently, SQC. With Chexy mortgage payments, you’re paying 1.75 cents per Aeroplan point. Objectively, this isn’t bad and is a reliable source of earnings.
Compared to buying Aeroplan points during a 100% bonus sale, you’re still acquiring points about 0.12 cents cheaper per point. By paying your mortgage with Chexy, you can earn a high quantity of points over the course of a year.
But I hesitate to recommend Chexy as the clear winner because you’ll earn points monthly rather than all at once. As a result, it can take quite a while to build up a meaningful balance. Also, the points you earn are tied to your mortgage payment amount, so the ability to scale up at 1.75 cents per point is limited.
Maybe, for SQC
SQC is the more exciting element here (just like with the Aeroplan Bell partnership), and in the above example, you’ll earn 500 SQC per month for a total of 6,000 a year (assuming a mortgage payment of $2,500). Now, this has the potential to create quite a big impact between unlocking the next tier of Aeroplan status and/or also unlocking any Milestone Rewards along the way. If this 6,000 unlocks a tier with Priority Rewards, that alone could easily be worth the $525 spent a year in Chexy fees.

Again, the limiting factor here is the cost of your mortgage, which limits how many SQC you can earn with Chexy. However, the 25,000 SQC maximum in the “Everyday Partners” category is difficult to maximize in the first place (how much LCBO are you realistically buying per year), so the impact of paying your mortgage with Chexy can be quite significant.
Is Chexy Worth it for You?
Whether Chexy is worth using ultimately comes down to what you’re trying to achieve.
For most of us, the biggest value comes from using Chexy strategically to unlock credit card bonuses or benefits that would otherwise be difficult to reach with everyday spending.
In terms of maximization, the best ways to make Chexy work for you are by unlocking new credit card welcome bonuses or credit card benefits that only occur after spending $X amount.
For example, you can earn 25K Aeroplan status by spending $125,000 on a premium Aeroplan co-branded card (TD Aeroplan Visa Infinite Privilege, CIBC Aeroplan Visa Infinite Privilege, American Express Aeroplan Reserve Card).
Case Study 1: Using Chexy to Meet a Welcome Bonus
Let’s say you’ve just been approved for the TD First Class Travel Visa Infinite Card, which is offering at present:
- 20,000 TD Rewards Points as a welcome bonus when you make your first Purchase with your Card
- 140,000 TD Rewards Points when you spend $7,500 within 180 days of Account opening
$7,500 might not sound like such a high spending requirement spread over six months, but it’s likely you want to earn the full welcome bonus in a faster timeframe, which is where Chexy comes in.
Again, assuming your rent is $2,000 per month, you’ll pay $35 per month in Chexy fees (assuming no referrals and thus a 1.75% fee). To reach the full $7,500 required, you will be paying rent for 4 months (assuming you are not doing any other spending on this card) and therefore paying a total of $140 in Chexy fees.
However, in exchange for that $140, you’ll be earning 160,000 TD points worth $800 when redeemed on Expedia for TD. Subtracting the Chexy cost, you’re coming out ahead by a cool $660. Keep in mind you will also spend less in Chexy fees by putting some of your regular spending on the card.
With a few referrals to friends and family, your processing fees drop even further.
Case Study 2: Paying Taxes with Chexy
The two certainties of life – death and taxes. While we cannot remove either, we can at least earn a plethora of points on the second.
If you forgo paying taxes directly to the CRA with bill pay and instead pay with your credit card through Chexy, you’ll earn an abundance of points (or money if using a cashback credit card) and can even combine it with Case Study 1 to unlock a new welcome bonus.
Say you owe $7,500 in taxes. At 1.75% (again, assuming you refer zero people), your fee would be $131.25. $5,000 is enough to earn welcome bonuses on quite a few cards:
- RBC Avion Visa Infinite, where you earn 20,000 Avion points (on top of the 35,000 upon approval) by spending $5,000 in the first 3 months
- Scotiabank Gold American Express Card, where you earn 65,000 Scene+ points by spending $7,500 in the first 12 months ($2,000 spend in the first 3 months)
Keep in mind, your fees drop to $112.50 if you refer just 3 people, and even lower if you refer more.
Case Study 3: Reaching a Spending-Based Benefit
Chexy can also help you reach a card spending threshold that unlocks something useful, such as a companion voucher or a once-annual sum of bonus points.
For example, premium Aeroplan cards earn 1,000 SQC for every $5,000 in eligible spending up to 25,000 SQC a year. Maximizing that means $125,000 of spending, so Chexy can go a long way towards reaching that goal.
It is a significant amount of spending, with a significant amount in processing fees, so it’s up to you to determine if it’s worth it. If you earn Aeroplan status organically, but are just shy of reaching the next Milestone Benefit, paying your next month’s rent with Chexy sounds like a good deal in exchange for a Priority Reward.
Paying a few months of rent through Chexy to unlock the next Aeroplan Milestone Benefit could be worth the processing fees
The Verdict – Is Chexy Worth the Fees?
Chexy can be an excellent tool for earning rewards on expenses that would otherwise earn nothing, but the key is making sure the rewards justify the processing fees. For most people, the biggest opportunities come from meeting credit card welcome-bonus spending requirements or unlocking valuable spending-based benefits, rather than earning points on every bill.
The new TD Aeroplan partnership makes Chexy even more attractive for eligible new cardholders, while mortgage payments offer an interesting way to earn Aeroplan points and SQC without flying. I wouldn’t necessarily recommend paying a 1.75% fee on every expense, but with the right credit card, a welcome bonus to chase, or a reduced fee through referrals, Chexy can be a valuable addition to your Miles & Points strategy.
It’s easy to see the value proposition if we use a cashback card as an example: the current Rogers promotion gives Rogers customers roughly 1.3% net cashback as pure earnings for everything paid through Chexy, such as rent, property tax, and CRA tax payments.

